UK Sustainability Reporting Standards
UK SRS 2027 — what changes, and when
UK SRS S1 and S2 are voluntary standards, published by the Department for Business and Trade on 25 February 2026.
The SRS 2027 date is now final: the FCA’s final rules (PS26/19, 30 September 2026) require listed companies in scope to report against UK SRS on a comply-or-explain basis from January 2027, finalising FCA CP26/5.
At a glance
What changes on 1 January 2027
UK SRS S1 and S2 were published by the Department for Business and Trade on 25 February 2026, for voluntary use.
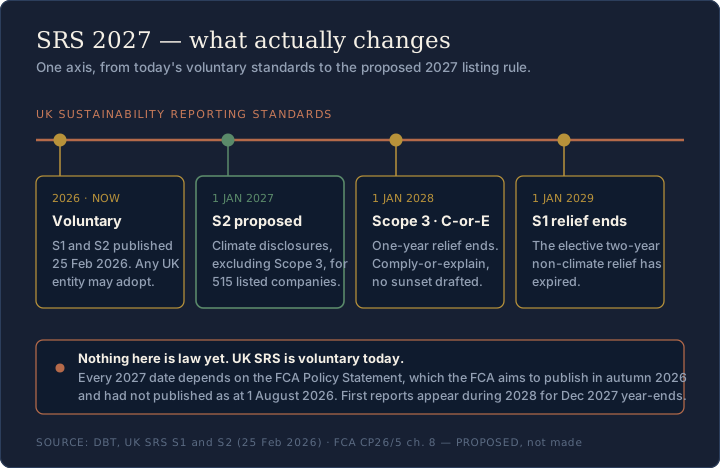
The FCA’s final rules (PS26/19, 30 September 2026) require listed companies in scope to report against UK SRS on a comply-or-explain basis for accounting periods beginning on or after 1 January 2027.
That puts the first reports in 2028.
Comply or explain applies across the UK SRS, S2 included: the consultation, CP26/5, had proposed making UK SRS S2 mandatory, and the final rules do not.
Two transitional reliefs soften the start: one year’s non-disclosure of Scope 3, and two years’ non-disclosure of UK SRS S1 non-climate matters.
Reference data
UK SRS by the numbers
The figures that define UK SRS today, each traced to the body that published it.
Standards published by the Department for Business and Trade
UK SRS S1 (General Requirements) and UK SRS S2 (Climate-related Disclosures) released for voluntary use immediately, alongside the Government Response to the consultation.
DBT · UK SRS S1 and S2 publication
Listed companies CP26/5 estimated would be affected — the consultation’s estimate
The final rules apply to companies listed under UKLR 6 (commercial companies), 14 (international commercial companies secondary listing), 15 (depositary receipts), 16 (non-equity and non-voting equity shares) and 22 (transition). CP26/5 had proposed only a signposting statement for UKLR 14 and 15; under the final rules they report on a comply-or-explain basis too. Closed-ended investment funds, open-ended investment companies, shell companies, and debt, securitised derivative and miscellaneous securities are excluded. PS26/19 gives no total count.
FCA · PS26/19 ¶3.6–3.7 · CP26/5 Annex 2 ¶43
Responses to the DBT consultation on the UK SRS exposure drafts
170 were submitted through an online survey platform and 39 sent directly to DBT by email; 199 came from organisations and 10 from individuals. Of those answering the question on the four TAC-recommended amendments, 68% (125 of 184) agreed with them.
Government Response · paras 1.6–1.7, 1.17
The TCFD four-pillar disclosure architecture, retained in UK SRS S2
Governance, Strategy, Risk Management, and Metrics and Targets. The structural foundation carried directly from TCFD (2017, disbanded 2023) — but disclosure requirements within each pillar are substantially enhanced.
UK SRS S2 · Paragraphs 5–37 · TCFD Recommendations
GHG Protocol Scope 3 categories an entity must consider under UK SRS S2
From purchased goods (Cat 1) to investments (Cat 15). Paragraph B32 requires all 15 to be considered and the categories included in the Scope 3 figure to be disclosed. Under the FCA’s final rules Scope 3 is comply or explain like every other UK SRS disclosure, with a one-year relief during which a company states only that it is using it.
UK SRS S2 · Paragraphs B32–B58 · GHG Protocol Scope 3
Jurisdictions adopting or moving to adopt ISSB Standards
Over 40 jurisdictions have decided to use, or are taking steps to introduce, ISSB Standards — together around 60% of global GDP, more than 40% of global market capitalisation and around 60% of global greenhouse gas emissions. Ethiopia and Peru were the latest additions as at end March 2026.
IFRS Foundation · ISSB Update · April 2026
Amendments the UK government proposed in June 2025 — the final count is not stated
DBT consulted on six proposed amendments to IFRS S1 and S2 in June 2025 (68% of respondents answering agreed with the four recommended by the TAC). The set changed before publication: the GICS amendment was withdrawn because the ISSB removed GICS itself in December 2025; the two-year beyond-climate relief was replaced by removing the time limit altogether; and paragraphs 73A, 73B, B59A and E5 were added. Annex A of the government response maps the final differences from IFRS S1 and S2 and carries no count.
Government Response · paras 1.17–1.23, Annex A
ISSA (UK) 5000 applies to sustainability assurance engagements on periods beginning on or after 15 December 2026
The FRC’s UK adaptation of the IAASB international sustainability assurance standard, published 12 November 2025 for voluntary use. It is effective for engagements on sustainability information for periods beginning on or after 15 December 2026, or as at a specific date on or after that day, with earlier application permitted — and it governs how an engagement is performed, not whether one must be obtained. The FCA’s final rules do not require assurance: where a company obtains it, it names the provider, the disclosures assured and the assurance standards used.
FRC · ISSA (UK) 5000
Last verified 30 September 2026 · Updates as regulators publish new figures
Status
Is UK SRS mandatory in 2027?
No — for listed companies in scope it is comply or explain, and for every other UK entity it is voluntary.
Until accounting periods beginning on 1 January 2027, no UK entity is required to report against UK SRS S1 or UK SRS S2, and none outside the listed categories is required to use them at all.
The 2027 date comes from the FCA’s final rules, published on 30 September 2026: listed companies in scope report against UK SRS on a comply-or-explain basis for accounting periods beginning on or after 1 January 2027.
The FCA makes its listing rules under section 73A of the Financial Services and Markets Act 2000.
The rules finalise the FCA’s CP26/5 consultation, which had proposed making UK SRS S2 mandatory; the final rules adopt comply or explain across all categories of disclosure instead.
The standards themselves were published by the Department for Business and Trade on 25 February 2026 as the UK endorsement of the ISSB's IFRS S1 and S2, and the department's Modernising corporate reporting consultation of 7 September 2026 says only that the government “will consider how UK SRS should be reflected in the Companies Act 2006”.
UK SRS S1 and S2: published by the Department for Business and Trade, voluntary.
FCA final rules (PS26/19): published 30 September 2026.
Listed companies in scope: comply or explain from 2027.
Key dates
UK SRS timeline: the key dates
The dates here are the FCA’s final rules, published on 30 September 2026.
Listed companies in scope report against UK SRS on a comply-or-explain basis for accounting periods beginning on or after 1 January 2027, with first reporting in 2028.
A company may use a one-year relief from disclosing Scope 3.
After that year Scope 3 is reported, or its omission explained, like every other disclosure — the consultation draft had proposed the rest of UK SRS S2 as mandatory, and the final rules put all of it on comply-or-explain.
The two-year relief for UK SRS S1 non-climate matters works the same way: a company using it says so, and no further explanation is required during the relief period.
Nothing in the final rules makes UK SRS disclosure mandatory.
The dated plan is on our UK SRS timeline and deadlines pages.
UK SRS S1 & S2 Published
Department for Business and Trade publishes final UK Sustainability Reporting Standards
FCA Final Rules Published
PS26/19 finalises CP26/5: listed companies in scope report against UK SRS on a comply-or-explain basis across all categories of disclosure, UK SRS S2 included
Comply or Explain Begins
The rules apply to accounting periods starting on or after 1 January 2027, for companies listed under UKLR 6, 14, 15, 16 and 22. CP26/5 estimated around 600 listed companies would be affected
First Reports Published
First reporting under the final rules is in 2028. A company using a transitional relief states that it is doing so, and no further explanation is required during the relief period
Scope 3 Relief Ends
The relief allows one year of non-disclosure of Scope 3 under UK SRS S2. After it, Scope 3 is reported or its omission explained, like every other UK SRS disclosure
UK SRS S1 Relief Ends
The relief allows two years of non-disclosure of non-climate matters under UK SRS S1. After it, those matters are reported or explained on the same comply-or-explain basis
How long UK SRS S2 implementation actually takes
The FCA's final rules are published and the first accounting periods begin on 1 January 2027, so companies that waited for them to begin preparation are already late. Our indicative estimate: twelve to eighteen months end to end — driven by Scope 3 data, which can't be compressed.
From kickoff to first UK SRS S2 report, on our indicative estimate. Driven by Scope 3 supplier engagement and quantitative scenario modelling — neither compressible.
Of Scope 3 data work — from supplier engagement onset through validation. Of the 15 GHG Protocol categories, Category 1 (purchased goods) and Category 11 (use of sold products) are typically the largest for many sectors, and the hardest to source.
Foundation phase before data work meaningfully begins. Materiality assessment and gap analysis are pre-requisites — running data collection without these creates wasted effort. All durations here are our indicative estimates, not a regulatory timeline.
Twelve to eighteen months end to end, from kickoff to a first UK SRS S2 report, is our indicative estimate.
It is not a regulator’s figure: no UK regulator publishes an implementation timeline.
It is informed by published implementation analysis from PwC and KPMG, and by the transitional reliefs in the FCA’s final rules, which finalised FCA CP26/5.
Scope 3 data is the longest workstream, and it cannot be compressed.
UK SRS S2 requires all 15 GHG Protocol Scope 3 categories to be considered, and the categories included in the Scope 3 figure to be disclosed.
The programme itself is set out in our UK SRS compliance guide.
Scope
Who is in scope for UK SRS in 2027
The final rules apply to companies listed in the commercial companies (UKLR 6), international commercial companies secondary listing (UKLR 14), depositary receipts (UKLR 15), non-equity and non-voting equity shares (UKLR 16) and transition (UKLR 22) categories.
Closed-ended investment funds, open-ended investment companies, shell companies, and debt, securitised derivative and miscellaneous securities are excluded.
The Policy Statement gives no total count; CP26/5, the consultation, estimated that around 600 listed companies would be affected.
Whether a company falls within scope is worked through on who must comply with UK SRS.
Continue reading
Start with the question you have
Who must comply?
Comprehensive scope guide for UK SRS requirements. Understand if your company falls within the FCA’s comply-or-explain scope.
Implementation timeline
Key dates from the FCA’s final rules of 30 September 2026 to first reports in 2028 and the end of the transitional reliefs. Plan your preparation with our detailed timeline.
Compliance roadmap
Step-by-step implementation guide with practical checklists. From materiality assessment to first report.
UK SRS S2 guide
Complete guide to climate-related disclosures. Scope 1, 2, and 3 emissions, scenario analysis, transition plans.
UK SRS S1 overview
General sustainability matters beyond climate. Biodiversity, human capital, supply chain impacts.
Assurance statement
Assurance is not required: under the FCA’s final rules a company that obtains it names the provider, the disclosures assured and the standards used. What limited and reasonable assurance involve if you commission one.
The UK SRS family
Where else to read
Our sister reference site covers UK SRS in depth.
Our sister title publishes editorial coverage of the UK sustainability reporting standards and of sustainability reporting standards more widely, including SECR, ESOS and the wider framework.
It keeps its own UK SRS timeline alongside ours.
For a plain-English introduction to the standards themselves, start with UK SRS S1 and S2.
For guidance on UK SRS who is in scope, see the sister reference site's scope assessment.
Financial-services firms can find sector-specific guidance on financed emissions and PCAF reporting.
Frequently asked
UK SRS 2027 — frequently asked
Is UK SRS mandatory in 2027?
No — for listed companies in scope it is comply or explain. The FCA's final rules (PS26/19, 30 September 2026) require them to report against UK SRS on a comply-or-explain basis for accounting periods beginning on or after 1 January 2027, with first reporting in 2028. The consultation, CP26/5, had proposed making UK SRS S2 mandatory; the final rules do not. For every other UK entity the standards remain voluntary.
When does UK SRS S2 apply?
Under the FCA's final rules, listed companies in scope report against UK SRS S1 and S2 on a comply-or-explain basis for accounting periods starting on or after 1 January 2027, with first reporting in 2028.
Does UK SRS require Scope 3 emissions in 2027?
Not in the first year if the company uses the relief. The FCA's final rules allow one year's non-disclosure of Scope 3 under UK SRS S2; a company using the relief states that it is doing so, and no further explanation is required during the relief period. After that, Scope 3 is reported, or its omission explained, on the same comply-or-explain basis as every other UK SRS disclosure.
How many companies are in scope of UK SRS in 2027?
The final rules cover companies listed in the commercial companies (UKLR 6), international commercial companies secondary listing (UKLR 14), depositary receipts (UKLR 15), non-equity and non-voting equity shares (UKLR 16) and transition (UKLR 22) categories. The Policy Statement gives no total count; CP26/5, the consultation, estimated that around 600 listed companies would be affected.
Sources
Primary sources
Every figure, date and status on this page traces to the instrument’s owner. Secondary commentary is never the source for a number.
- Department for Business and TradeUK Sustainability Reporting Standards: UK SRS S1 and UK SRS S2
Published 25 February 2026 for voluntary use. The standards this site covers.
- Department for Business and TradeUK SRS S1 General Requirements — final standard (PDF)
- Department for Business and TradeUK SRS S2 Climate-related Disclosures — final standard (PDF)
Paragraph B32: the Scope 3 categories an entity must consider.
- Department for Business and TradeGovernment response to the UK SRS consultation
209 responses; Annex A maps the final UK differences from IFRS S1 and S2.
- Financial Conduct AuthorityPS26/19: Aligning listed issuers' sustainability disclosures with international standards
First published 30 September 2026. The final rules: listed companies in scope report against UK SRS on a comply-or-explain basis for accounting periods starting on or after 1 January 2027, first reporting in 2028.
- Financial Conduct AuthorityCP26/5: Aligning listed issuers' sustainability disclosures with international standards (PDF)
The consultation PS26/19 finalises (30 January 2026, closed 20 March 2026). It proposed mandatory UK SRS S2; the final rules adopted comply or explain. Annex 2 ¶43 estimated around 600 listed companies affected.
- Financial Conduct AuthorityCP26/5 — consultation page
The consultation page for the proposals the final rules replaced.
- legislation.gov.ukFinancial Services and Markets Act 2000, section 73A
The power under which the FCA’s listing rules are made.
- IFRS FoundationInternational Sustainability Standards Board
IFRS S1 and S2, the baseline UK SRS endorses.
- IFRS FoundationUse of ISSB Standards by jurisdiction
Over 40 jurisdictions using, or taking steps to introduce, the ISSB Standards.
- Financial Reporting CouncilISSA (UK) 5000 — General Requirements for Sustainability Assurance Engagements (PDF)
Issued 12 November 2025 for voluntary use.
- GHG ProtocolCorporate Value Chain (Scope 3) Standard
The 15 Scope 3 categories.
- Department for Business, Innovation, Science and TradeModernising corporate reporting — consultation
Published 7 September 2026: the government “will consider how UK SRS should be reflected in the Companies Act 2006”.